Physical Gold is The Ultimate Hedge & a Critical Diversifier
Several surveys from 2008 and 2020 estimate that only 1 in 10 of Americans own physical gold.
The simple truth is this: Americans are just beginning to wake up. Physical gold has been the most sought-after form of wealth, diversification, and money throughout history— valued across every culture and era. It has served— and continues to serve— as the foundation of central banks around the world. Gold is the protector of currency value across time and turmoil, making it an essential component of any well-balanced and diversified portfolio.
All data in the chart below refers specifically to physical gold.
It’s important to understand that gold ETFs, mining stocks, and mutual funds are forms of paper gold, and they do not perform the same. In fact, many of these financial products and mining operations have failed since 1971. A quick look at their prospectuses reveals why: paper gold does not perform like the physical asset— nor does it serve the same purpose in times of currency failure, war, or civil unrest. ETFs state that they are an investment vehicle for those who cannot afford physical gold and silver.
Prices are based on March 26, 2025, when gold stood at $3,019.57.
Gold was the top-performing asset in 2025. For this report, we chose not to base our analysis on gold’s full upside move in order to remain conservative and allow room for normal market pauses. After strong advances, gold often goes through pullbacks and rebounds. This type of price action is normal and has often set the stage for the next major move higher.
Why are we using the year 1971?
That’s the year the U.S. removed the dollar from the gold standard.
Through Great Years & Terrible Years... Gold Shines
How important has gold been since 1971, when the U.S. severed the dollar from gold? Shocking the world and breaking the Bretton Woods Agreement...
Since the U.S. abandoned the gold standard in 1971, we see Gold has outperformed the S&P, DOW, and Treasuries:
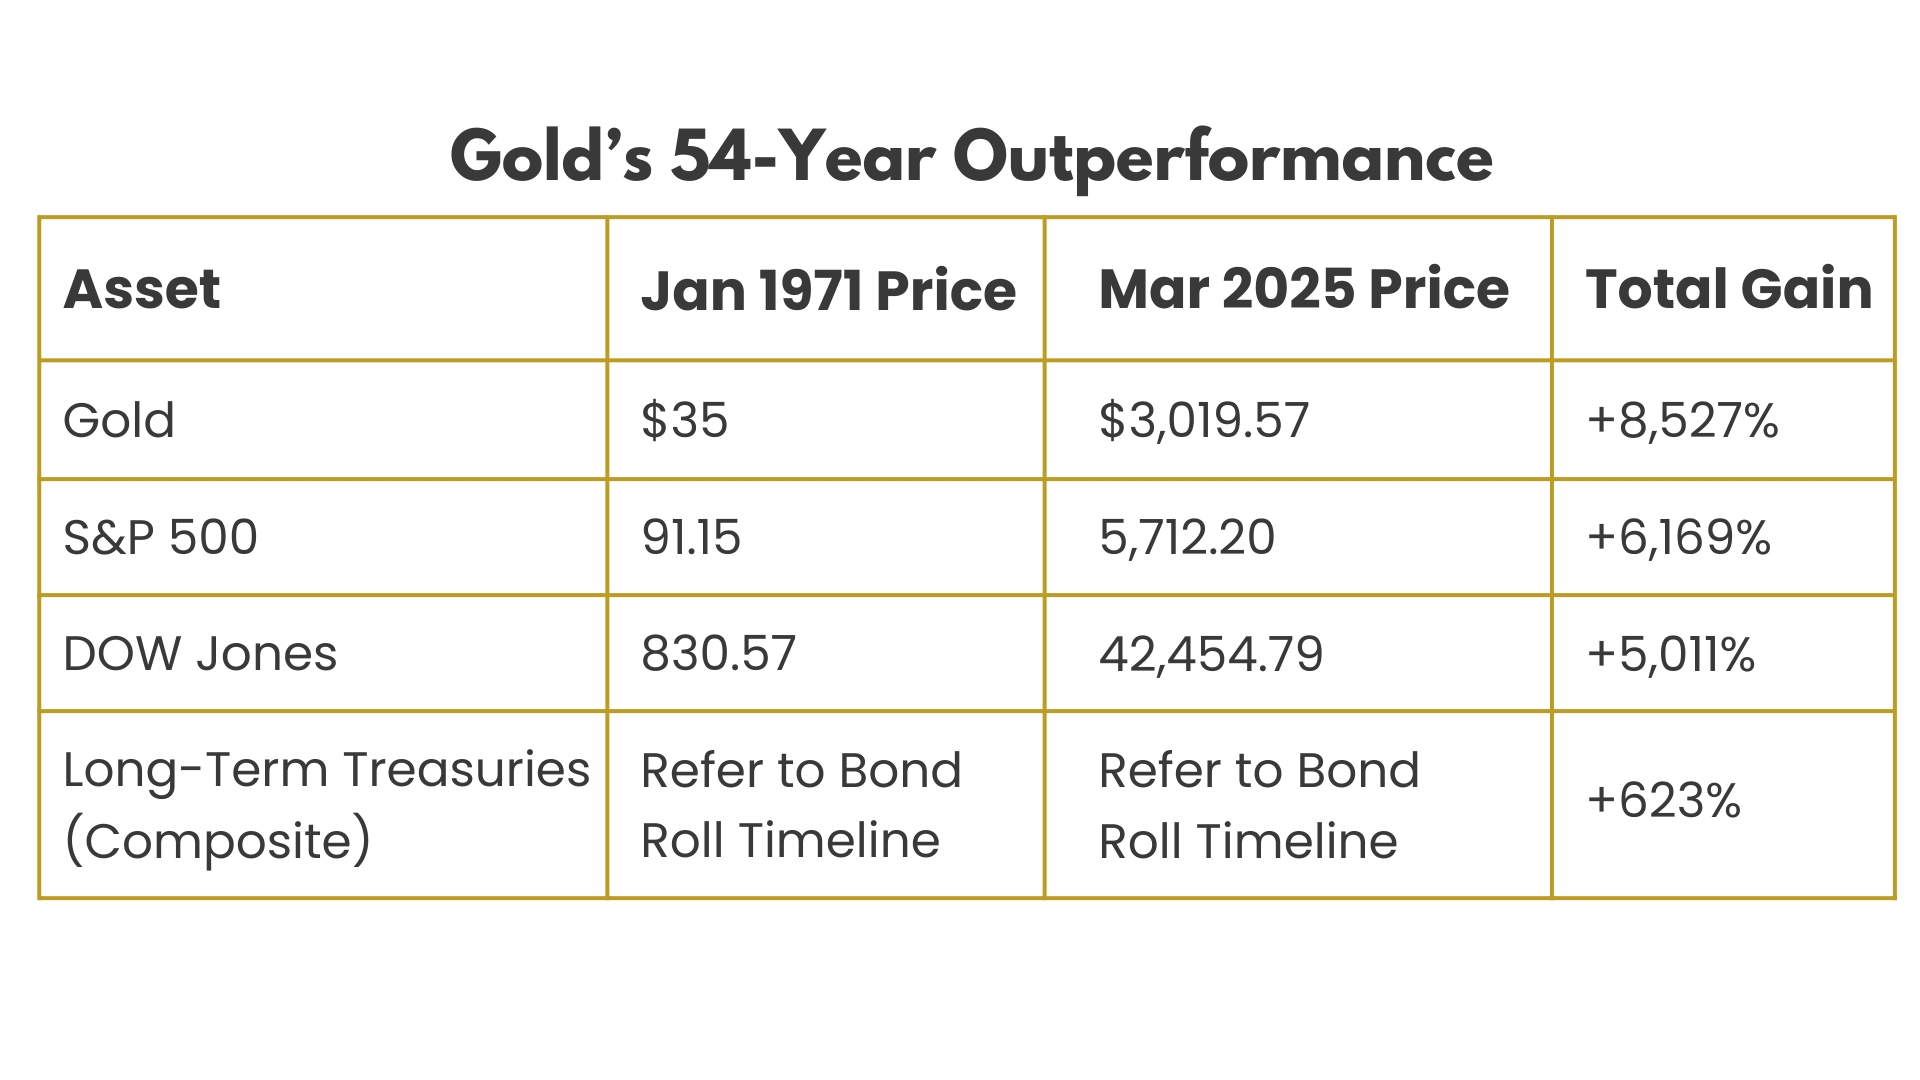
Gold— often dismissed as a “non-yielding” asset— has, in fact, outperformed both major stock indexes and long-term bonds throughout the entire fiat-money era. Even during the S&P 500’s strongest decades, gold surged in the inflationary 1970s, preserved wealth during the dot-com collapse, outperformed through the 2008–2012 financial crisis, and again during the 2020 COVID crisis.
Bond Roll Timeline:
-
- In January 1971, you purchase a 20-year Treasury bond at the prevailing rate of 6.5%.
-
In January 1991, you roll the proceeds into a 30-year Treasury bond, also yielding 6.5%.
-
Finally, in January 2021, you reinvest those funds into another 30-year Treasury bond at a rate of 1.65%.
- Held through January 2026, Total nominal profit (1971–Jan 2026): ≈ +635%
The U.S. Bond Market Is Not What It Once Was...
For decades, the bedrock of global finance has been the unchallenged belief that the U.S. Treasury Bond is the "safest investment in the world." This claim is recited by policymakers and financial experts as an article of faith. Yet, when we look beneath the surface at the extraordinary actions taken by the Federal Reserve (the Fed) since the 2008 financial crisis, the truth becomes impossible to ignore: the U.S. bond market is no longer a self-sustaining entity; it is a market that requires continuous life support from the very government whose debt it sells.
The simple fact that the Fed has had to become the largest single holder and purchaser of U.S. sovereign debt completely nullifies the idea of it being a purely "risk-free" asset.
Re-Weighting the Portfolio: 60/20/20 to Add 20% Gold and Minus 20% of Bonds
Investors looking to diversify 60/20/20 can now compare the strategy directly against the standard 60/40 portfolio. New data shows that a 60/20/20 mix of stocks, gold, and bonds delivered a 38% higher compounded nominal return while also reducing volatility.
If we model a 54-year portfolio comparison:
- Traditional 60/40 (Equities/Bonds)
Weighted Return ≈ (0.60 × 6,169%) + (0.40 × 623%) = ≈ 3,719% - Gold-Augmented 60/20/20 (Equities/Physical Gold/Bonds)
Weighted Return ≈ (0.20 × 8,527%) + (0.20 × 623%) + (0.60 × 6,169%) = ≈ 5,132%
Gold shows a 38% higher compounded nominal return
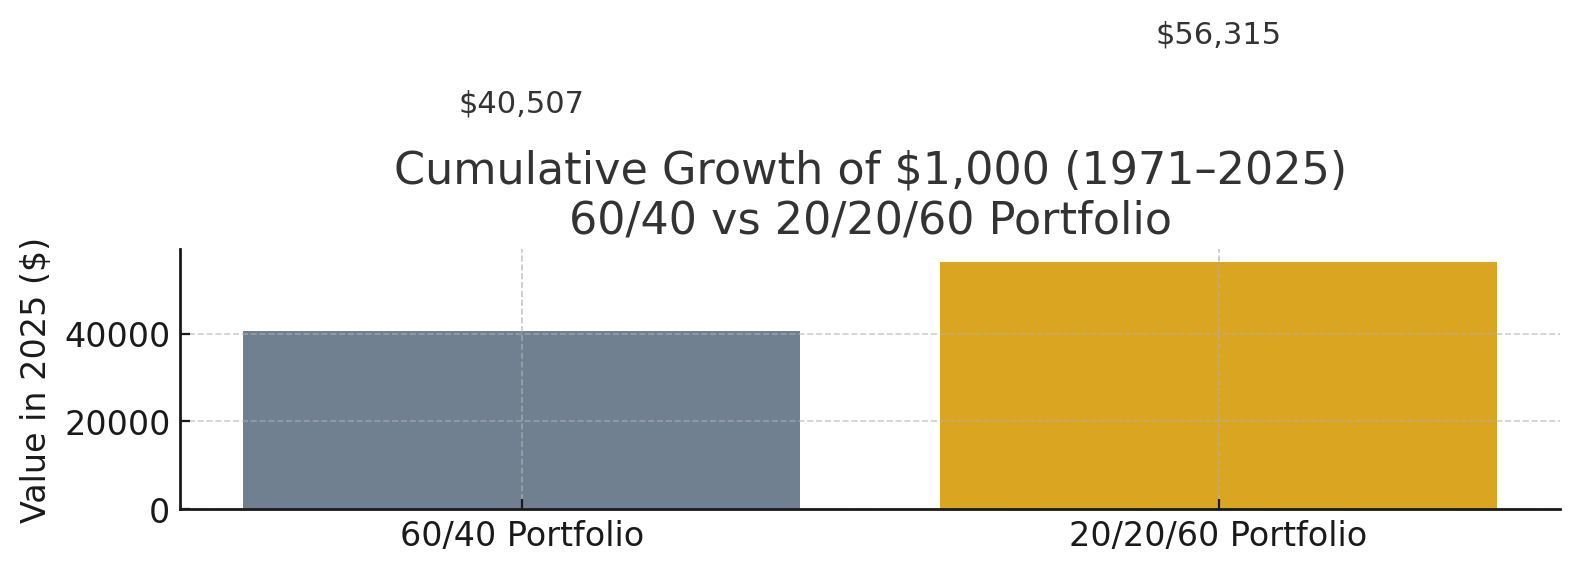
That’s a 38% higher compounded nominal return than the 60/40 model— while historically reducing volatility in every inflationary cycle.
Why Gold Makes The Critical Difference
- Inverse Correlation to Bonds and Stocks— Gold historically rises during equity drawdowns and inflation shocks. Bonds, in contrast, lose value when inflation and rates rise simultaneously.
- Gold Protects Against Dollar Erosion— As the dollar loses purchasing power over time, gold has historically helped preserve wealth.
- Real Asset, Not a Promise— Bonds rely on governments to maintain purchasing power; gold is purchasing power.
- Liquidity in Crisis & War— Gold remains globally tradable when currencies, sovereign debt, or banking systems lose trust.
- Central Bank Validation— Global central banks have been net buyers of gold every year since 2010— signaling where true “reserve” confidence lies.
- Gold Benefits from De-dollarization— As more nations reduce reliance on the U.S. dollar, gold’s role as a trusted global reserve asset becomes even stronger.
- Gold Defends Against Inflation & Policy Mistakes— When debt grows, money supply expands, or confidence in government policy weakens, gold has historically provided protection.
- Gold Improves Portfolio Resilience— It helps lower overall volatility and strengthen a portfolio through uncertain market cycles.
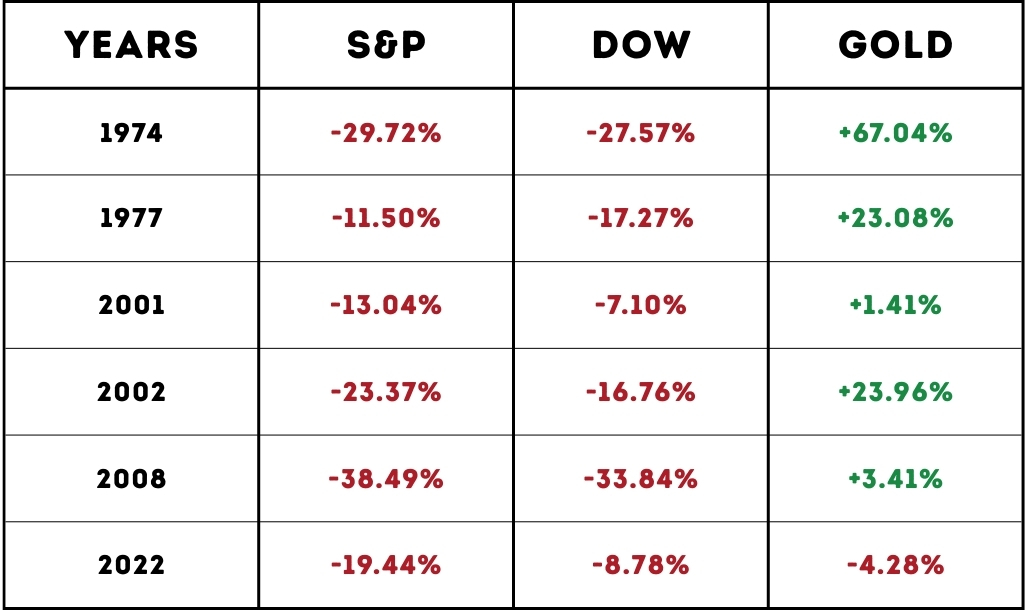
Worst Years in the Stock Markets
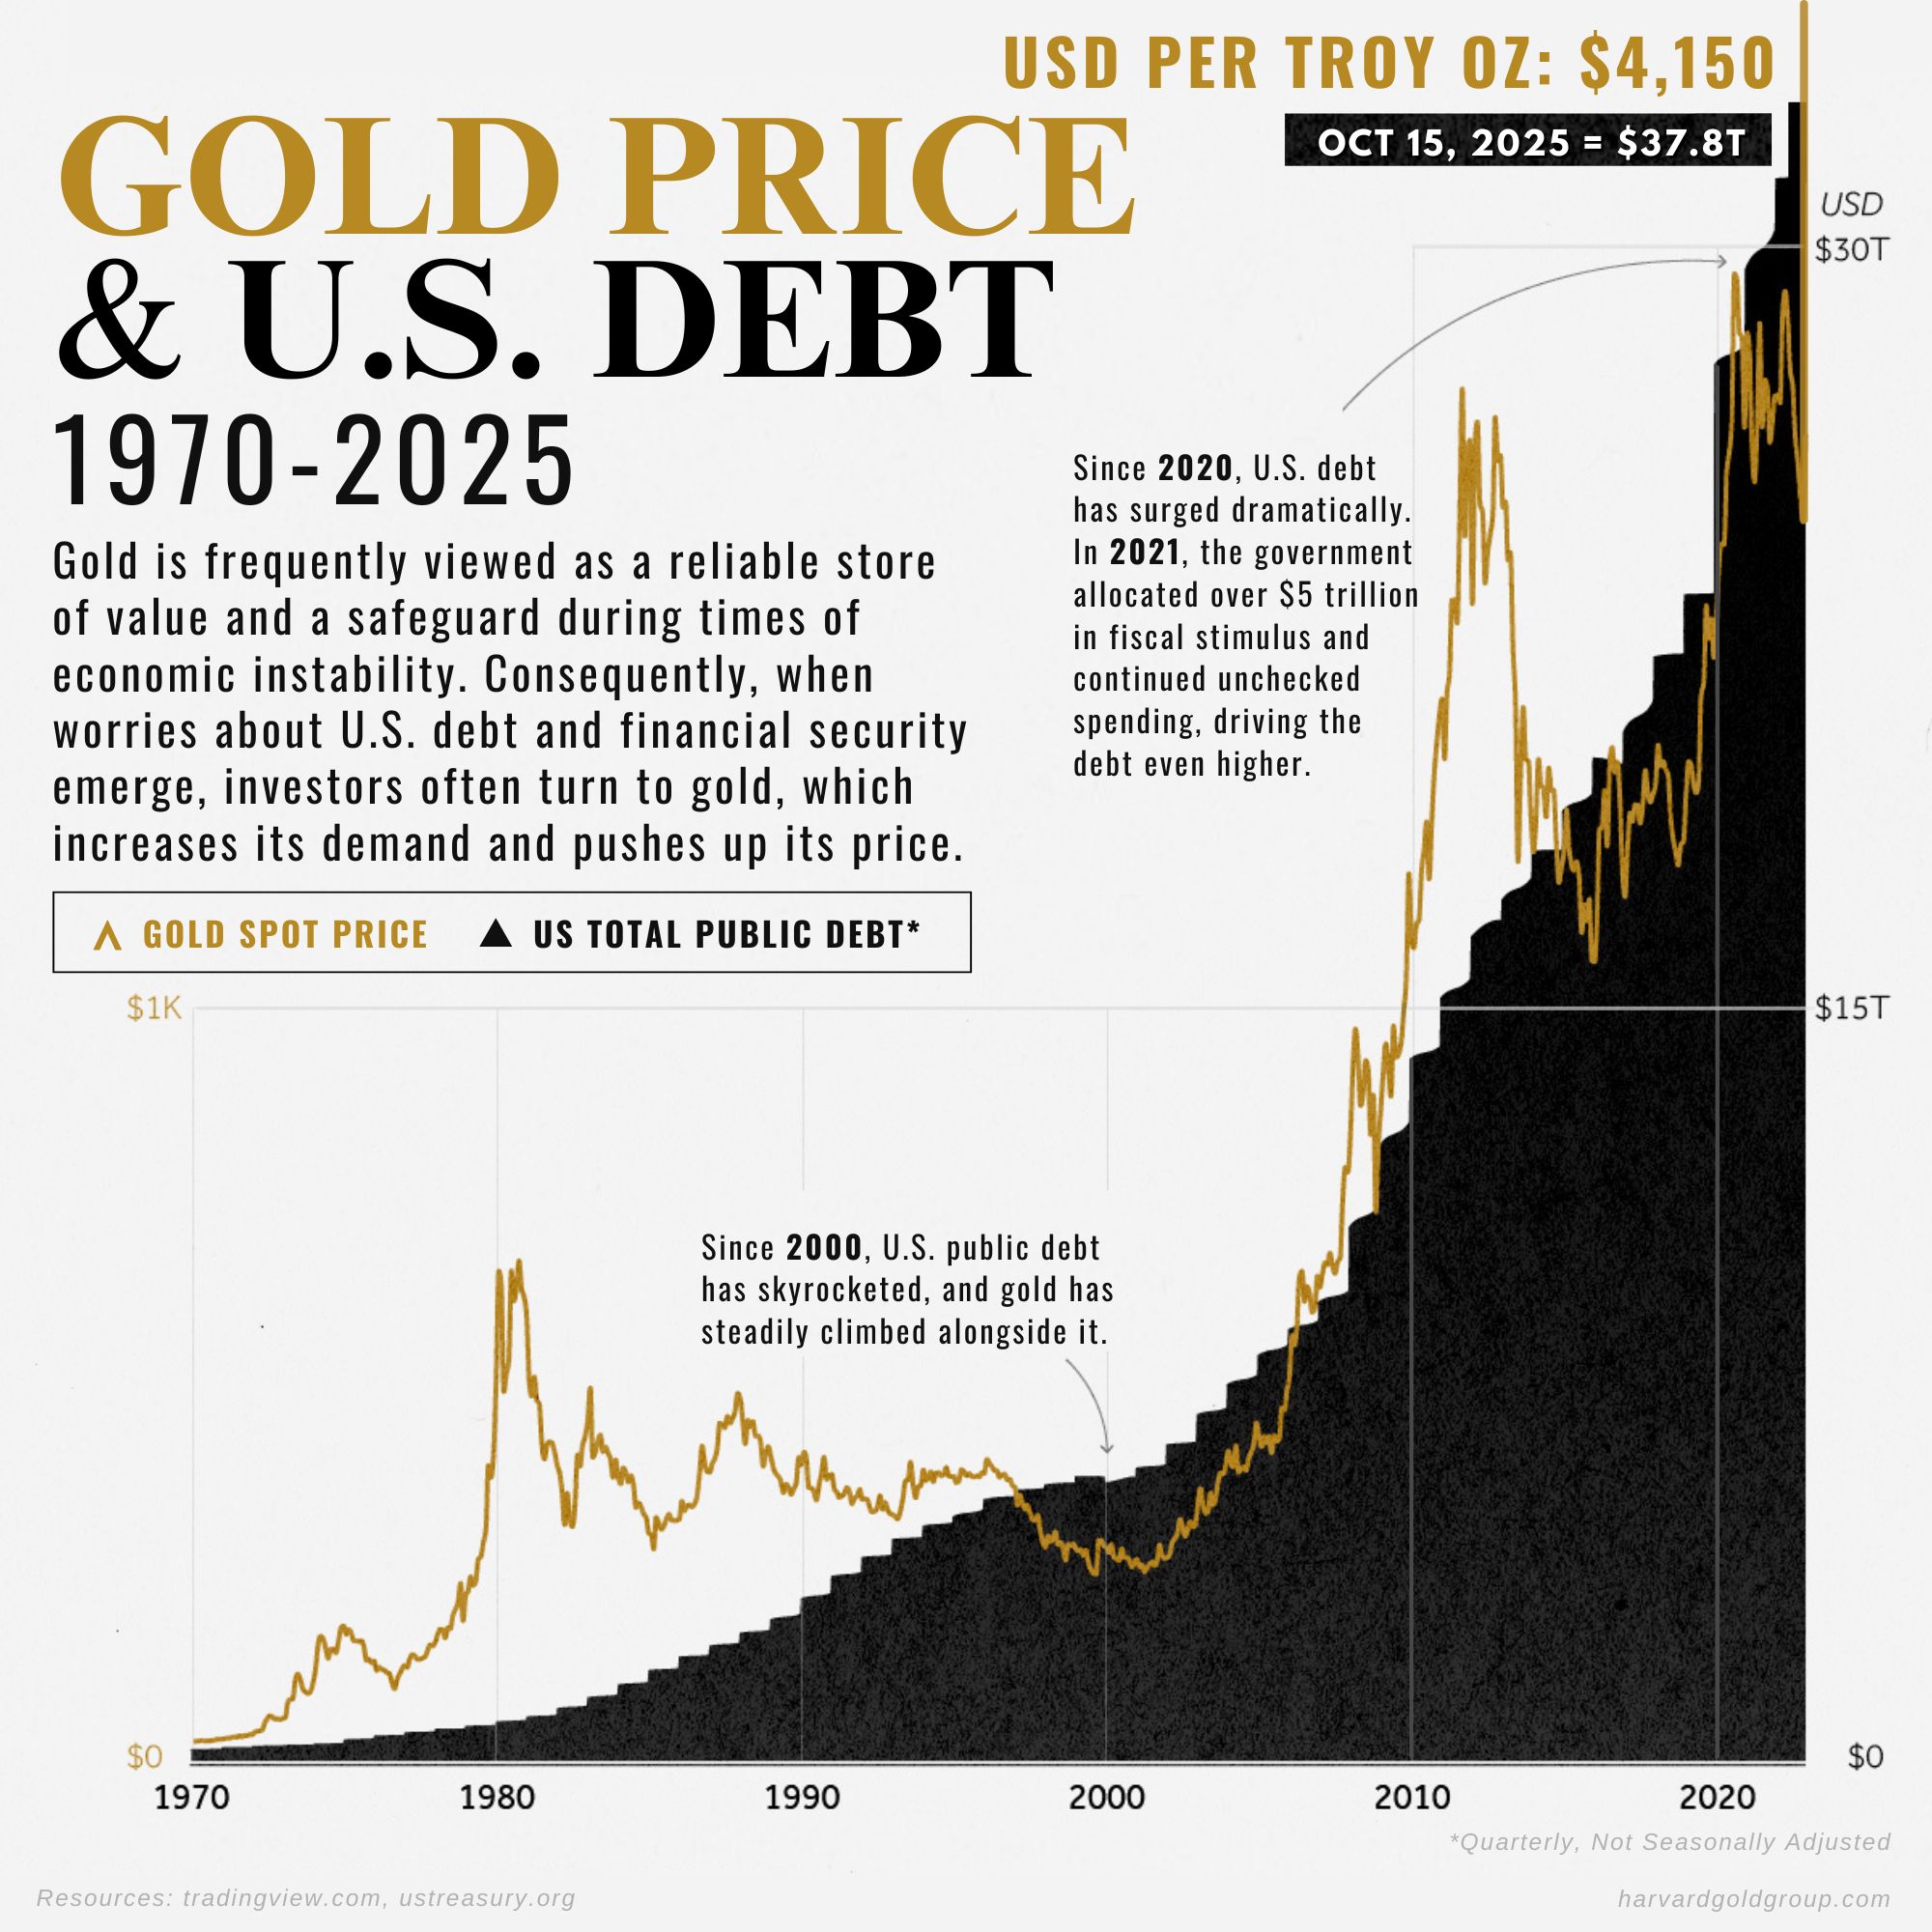
Gold Price & U.S. Debt
Purchasing Power of the Dollar
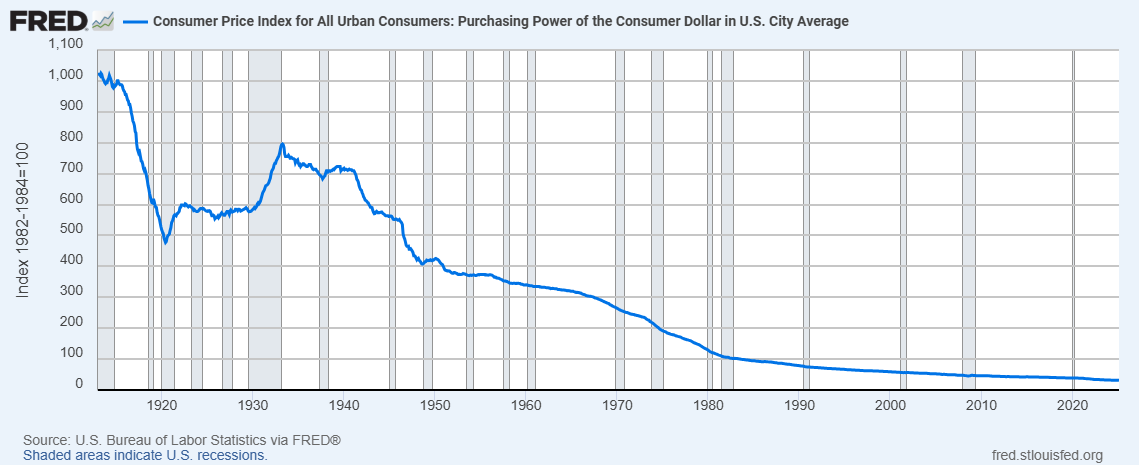
The most important reason to hedge and diversify your wealth with gold is the declining purchasing power of the U.S. dollar. Over time, the dollar’s value has eroded significantly due to inflation—primarily driven by excessive money creation (money printing) and debt expansion. These two forces are deeply interconnected. Historically, all fiat (paper) currencies have eventually failed due to inflation, leading to currency resets or radical shifts in monetary policy.
From January 2000 to February 2025:
(last update to the Fed website)
USD Purchasing Power Has Declined 47%
- January 2000: The CPI was approximately 168.8
- March 2025: The CPI is approximately 319.1
Source: FRED+1Bureau of Labor Statistics+1
An 89.1% increase in the CPI means that purchasing prices have nearly doubled since 2000. Consequently, the dollar's purchasing power has decreased by approximately 47% over this period.
From August 1971 to February 2025:
(last update to the Fed website)
USD Purchasing Power Has Declined 85-90%
- August 1971: The U.S. abandoned the gold standard, leading to significant inflationary pressures.
While exact figures can vary based on different CPI calculations, it's widely reported that the dollar has lost approximately 85% to 90% of its purchasing power since 1971. This means that what could be purchased for $1 in 1971 would cost between $6.50 and $10 today.
Source: FRED+1Bureau of Labor Statistics+1
Had an investor allocated just 20% to gold since 1971, (When the U.S. abandoned the gold standard) the portfolio would have:
✅ Outperformed the traditional 60/40 model by roughly 49%,
✅ Endured less correlation risk, and
✅ Preserved real purchasing power across six major inflationary and recessionary periods.
In an age where governments rely on perpetual debt expansion, a “balanced” portfolio without physical gold is no balance at all.
The 60/20/20 model isn’t speculation — it is TRUE protection
The Modern Investor’s Reality: When Safety Is Engineered, True Protection Must Be Chosen
In today’s financial system, safety is no longer organic— it’s manufactured. The same policies that hold the bond market together are the very ones eroding the purchasing power of the dollar that those bonds are paid in. Every rate cut, every new round of quantitative easing, and every fiscal bailout may buy time, but it also deepens dependency and accelerates the devaluation of paper assets. That is why the world’s most sophisticated institutions— from global central banks to sovereign wealth funds— continue to quietly accumulate gold. They understand what most investors forget: gold is not a speculation; it’s insurance against the failure of paper promises.
When the next crisis hits, the question won’t be whether the Fed intervenes— it will be how much more the currency must be sacrificed to preserve the illusion of stability. In that moment, those who hold physical gold will not be waiting for reassurance from the central bank. They will already own the one asset that stands outside the system, immune to default, devaluation, and deceit.