
What to Expect During a Recession
- Stock markets decline, with prices dropping 20-50% or more, along with reduced or eliminated dividends.
- Retirement funds suffer, hit by both market downturns and inflation, creating a double financial blow.
- Unemployment rises, making job security more uncertain.
- Wages, benefits, and hours decrease, while bonuses are often eliminated.
- Debt burdens surge, impacting individuals, corporations, and governments.
- Foreclosures, car repossessions, and bankruptcies increase as financial strain intensifies.
- Government tax revenue declines, leading to cuts in public services and programs.
- Families and communities struggle, as more parents, children, and friends find themselves in need.
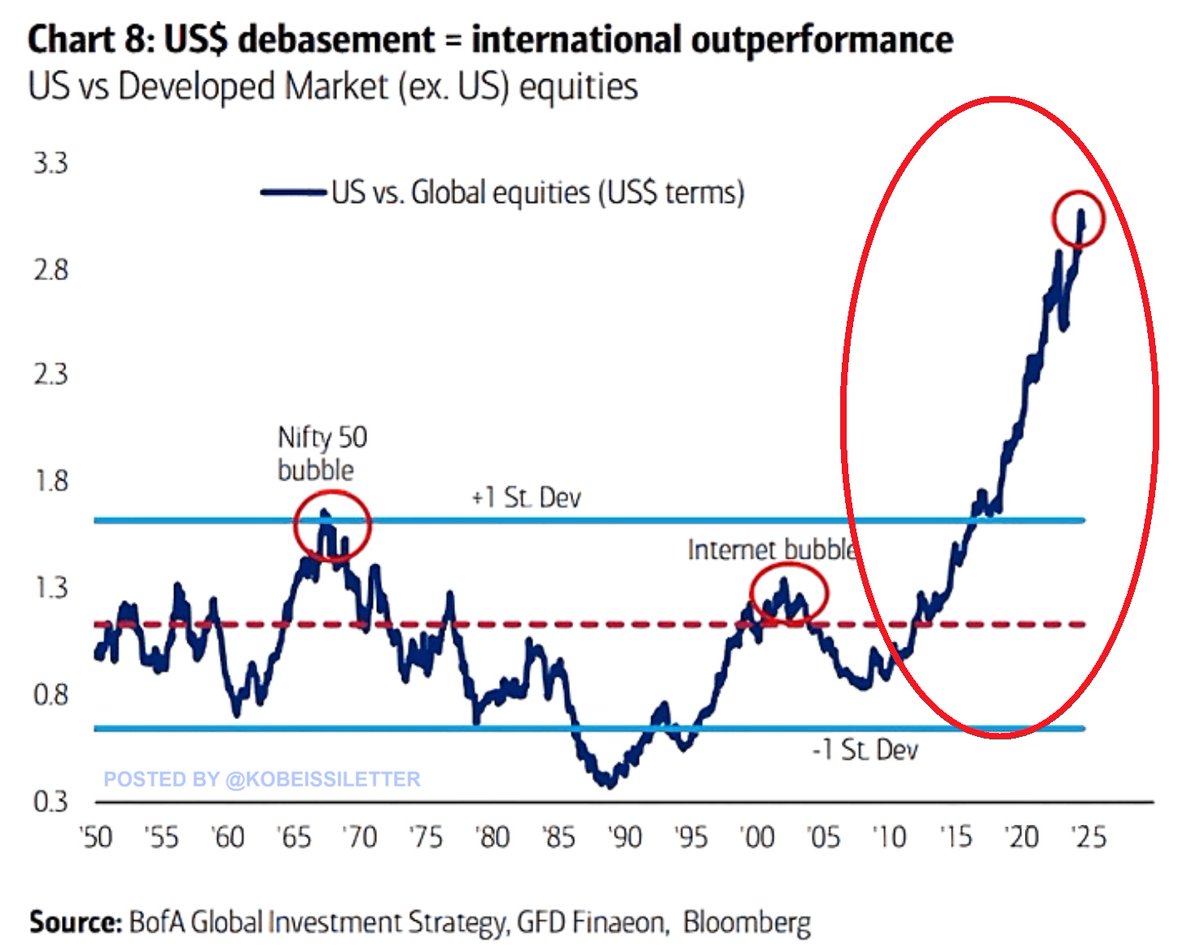
US to Developed Market -
Where We Are Now
The U.S. stock market is enormous (see chart below). The ratio of U.S. stocks to developed market equities recently reached a record high of approximately 3.0x. Over the past decade, this ratio has doubled as U.S. stocks are extremely overvalued compared to their global counterparts.
What Causes Recessions?
Stock Market Crashes → Wealth Destruction & Panic
- Market crashes lead to a rapid loss of confidence, reducing household wealth and spending.
- Businesses struggle as capital dries up, leading to layoffs and declining economic output.
Prolonged Low Interest Rates → Create Asset Bubbles & Debt Crises
- When interest rates remain too low for too long, borrowing becomes cheap, leading to excessive debt in housing, stocks, and corporate markets.
- This creates asset bubbles, which eventually burst, triggering widespread financial instability.
Excessive Debt (Household, Corporate, and or Government) → Debt Crises & Defaults
- When businesses, households, or governments accumulate unsustainable debt, they struggle to repay loans.
- This results in defaults, bankruptcies, and a financial crisis.
Money Printing Fuels Asset Bubbles → and Bigger Boom-and-Bust Cycles
- Excessive money printing often flows into stocks, real estate, and speculative assets rather than productive assets.
- That artificially inflates prices, fuels asset bubbles, and increases the risk of painful bursts.
Example: The 2000 Dot-Com Bubble & 2008 Housing Bubble were both fueled by easy money, cheap credit, and excess liquidity.
Even more alarming, the scale of money printing and debt expansion used to contain the 2020 crisis was staggering— dwarfing the response to 2008.
That brings us to where we are today: we are either still in the late stages of the boom cycle or in the early stages of the bust.
Inflation Surges, Raising Interest Rates → Reduced Purchasing Power & Economic Slowdown
- Rapid price increases reduce consumer spending power, making essentials like food and energy unaffordable.
- To fight inflation, central banks raise interest rates, often pushing the economy into a recessionary spiral.
- Higher rates also lead to loan defaults and bankruptcies for businesses and individuals, creating tighter financial conditions.
Banking & Credit Crises → Liquidity Shortages & Business Failures
- Bank failures tighten lending conditions, causing credit to dry up and restricting both business activity and consumer borrowing.
- Bank runs: When banks make risky investments and confidence breaks, depositors rush to withdraw funds— often accelerating the institution’s collapse.
- Banking failures have contributed to financial crises and recessions since the inception of banks.
Trade Wars & Tariffs → Slower Growth & Higher Prices
- Restrictions on global trade create higher costs for businesses and consumers, while reducing economic efficiency.
- Retaliatory tariffs create uncertainty, stifling business investments and job creation.
Geopolitical Conflicts & Wars → Economic Disruptions & Supply Chain Disruptions
- Military conflicts lead to government overspending, inflation, and trade disruptions.
- Uncertainty from global tensions causes business slowdowns and stock market volatility.
- Wars, natural disasters, or pandemics can disrupt supply chains, leading to shortages and higher prices.
- Businesses struggle to meet demand, resulting in layoffs and factory closures.
Two Ingredients that Cause Larger Recessions & Consequences
Recessions are a natural part of economic cycles, arising from disruptions— economic, financial, or external— that stall growth and trigger contractions. What has transformed ordinary downturns into far more devastating crises in recent major episodes is the overuse of two aggressive policy tools by central banks and governments: prolonged ultra-low interest rates and massive money printing. These interventions, repeatedly deployed over the last three major recessions, have consistently amplified damage, inflated bigger bubbles, and set the stage for even more severe instability ahead.
They go hand in hand to create dangerous cycles:
- Low rates & money printing → inflated asset prices & speculative bubbles.
- Inflation rises → Purchasing power weakens.
- Central bank raises rates → sparking crashes, credit freezes, & deep recessions start.
Authorities print more and stack more debt to "rescue" the economy → restarting the cycle → at a larger scale and accelerating currency debasement.

Repeated Bubbles → The End Game: Monetary Reset
Each intervention to patch one recession plants the seeds for a larger, more explosive boom-bust cycle.
As money printing and debt continue unchecked, it will eventually trigger a horrific debt crisis with painful inflation that leads to the eventual collapse of the financial system, ultimately forcing a major monetary reset. Historically, those moments end— with gold returning to the center of financial trust. That is exactly why central banks worldwide are buying physical gold at historic levels.

Buy Gold During Recessions to Thrive
Recessions are typically defined as at least two consecutive quarters of declining economic output. While some recessions prior to 2000 used to be milder, more recent downturns have been extremely volatile, with both economic activity and stock markets experiencing significant losses.
During economic contractions, business performance weakens, unemployment rises, and consumer spending declines. This leads to lower corporate profits and falling stock prices, negatively impacting portfolios.
Even during recessions, especially ones with severe volatility, people must find ways to safeguard their assets— Particularly those saving for retirement with significant holdings in tax-advantaged accounts such as IRAs, 401(k)s, pension funds, annuities, TSPs, and inherited retirement accounts. Since these accounts are often heavily invested in the stock market, market crashes can put retirement savings at serious risk.
When stock markets decline or show signs of crashing, people seek safer assets that can preserve value during a recession— such as gold and cash. However, for those with tax-advantaged retirement accounts, holding cash isn't always an option due to potential tax liabilities. So, what’s the best solution?
They turn to a Gold Retirement Account/IRA, which allows them to roll over existing retirement accounts into physical gold without paying taxes or losing the tax deferred benefits. Unlike paper assets, gold has no third-party counterparty risk and historically gains value during recessions. A Gold IRA provides the same tax advantages as traditional retirement accounts while offering protection against stock market volatility, currency depreciation, inflation, bond market crashes, and offers asset appreciation in gold prices— making you diverse in uncertain times.
Gold as a Reliable Portfolio Diversifier
Finding truly effective diversifiers can be challenging, as many assets become increasingly correlated during periods of heightened market uncertainty and volatility. This is largely due to risk-on/risk-off behaviors, where investors shift between riskier and safer assets. As a result, many traditional diversifiers fail to provide protection precisely when it is needed most.
Gold stands apart because it frequently moves in the opposite direction of equities (stocks) and other risk assets, particularly as the dollar loses value and government debt continues to rise.
It has consistently outperformed during recessions and periods of uncertainty. While this has been evident since the U.S. severed the dollar from gold in 1971, gold’s role as a safe-haven asset has become even more crucial since 2000.
Since 2000, the U.S. has faced three major recessions:
- 2001 Dot-Com Crash
- 2008 Financial Crisis (Great Recession)
- 2020 COVID Crisis and its aftermath
The Federal Reserve’s response to each crisis has been to print money to mitigate the downturn. However, each time, the velocity and scale of money printing have increased exponentially to achieve the same economic effect. This excessive monetary expansion devalues the dollar’s purchasing power and remains a primary driver of inflation. When recession and inflation hit simultaneously, it creates a double financial blow for savings and retirement accounts.
Gold prices have continued to rise as smart money, financial institutions, countries, and individuals prepare for an inevitable recession— or worse. Since 2000, buying gold sooner rather than later has proven to be a prudent financial strategy.

Gold Demand During Recessions: 3 Key Factors
Physical gold is one of the few assets that individuals and countries rely on to safeguard their portfolios and net worth during economic downturns. Its demand in and of itself causes the price of gold to rise. Here are three key factors that drive demand for gold.
1) Flight to Safety
No one wants to experience losses. While we all understand that risk is an inherent part of acquiring assets, the reality of losing money can be difficult to endure. This is why many people aim to minimize risk. Although completely avoiding losses is impossible— especially during recessions— gold’s rising value can help offset declines in other assets and even grow your net worth.
The run to gold: Gold has performed extremely well {See graph above}
The run to cash: Inflation has eroded the purchasing power of cash dramatically since 2020. Since 2000, the dollar has lost more than 40% of its purchasing power, while gold is well above a 700% increase.
The run to bonds: Those that ran to bonds in 2020 as a flight to safety, for the most, faced a different outcome. In March 2020, interest rates were close to zero. Due to trillions of dollars being printed and the country racking up debt, by 2022 inflation hit hard, and interest rates had to be raised quickly… in 2023 the U.S. faced one of the worst bond market collapses in the last 100 years and the worst bank failures since the ’08 financial crises.
2) Uncertainty, Fear, and Volatility
Fear and uncertainty about the future, along with market volatility, are key drivers of increased demand for gold. When stock markets decline, housing markets weaken, or economies enter a recession— the duration and severity remain unknown. A downturn could resolve in six months, or it could stretch for years.
Even countries cannot predict with certainty when or how these major economic events will begin or end, which is why they too purchase massive amounts of physical gold. The stability gold provides makes it one of the most important assets in history. An added advantage for smart acquisition is that physical gold has performed well not only during economic downturns but also in prosperous times.
3) Strategic Diversity
No one should put all their eggs in one basket— not even in gold. However, by protecting a significant percentage of your net worth with physical gold, not only can you effectively spread your portfolio, but you can also achieve large profits over the long term.
Not everyone wants to protect a sizable portion of their net worth or portfolios with gold. Some only feel comfortable purchasing 10-20% to look for more of a cushion. Those kinds of decisions are up to each individual to make, but it is important to know that as more and more people are buying gold as a diversifier, the price is increasing.
What percentage of gold should you own?
Explore our What % of Gold? report for the charts and real-world data. You’ll see how a 10% allocation to gold increased total wealth by 34%, while a 20% allocation increased it by 108%.
The 5 Ways to Prepare So You Can THRIVE
1. Add Gold to Your Portfolio
Gold has historically protected wealth during recessions, inflation, and financial crises. Unlike paper assets, gold retains its value, serves as the ultimate form of money, carries no third-party counterparty risk, and cannot be controlled by any single country.
✔ Suitable against inflation— gold often rises as fiat currencies lose value.
✔ Preserve purchasing power when markets decline.
✔ Diversify your portfolio with a tangible, non-dollar denominated asset that has stood the test of time.
✔ Protect retirement savings by adding physical gold to an IRA or buy for direct delivery.
2. Build an Emergency Fund
A financial safety net is crucial when income becomes uncertain. Avoid dipping into retirement accounts during a market downturn, as withdrawals lock in losses and may trigger penalties.
✔ Aim to save at least one year’s worth of expenses.
✔ Look for passive income sources to supplement cash flow.
✔ Keep funds liquid— avoid locking them in CDs that lose value against inflation.
3. Stock Up on Essentials
Supply chain disruptions and inflation can lead to shortages and price spikes. Be proactive.
✔ Stockpile nonperishable food and essential household items.
✔ Keep a reserve of medical and personal necessities.
✔ Plan ahead— rising costs and scarcity may affect everything from groceries to electronics.
4. Optimize Cash Flow
Managing income and expenses wisely helps stretch your resources.
✔ Cut unnecessary expenses.
✔ Delay major purchases if possible.
✔ Avoid taking on new debt.
✔ Reduce losses on weak assets, but don’t panic sell.
5. Pay Down Debt
If possible, without draining your emergency fund— reduce debt to alleviate financial strain and increase flexibility.
✔ Debt keeps growing even if your income declines.
✔ Higher interest rates make borrowing more expensive.
✔ Freeing up credit provides a safety cushion for emergencies.
✔ New credit lines may become harder to access and more costly.
Data from the Pew Research Center and other sources show that the American middle class has steadily declined after each recession since 2000. With every downturn, fewer adults remain in the middle class, as more people fall into the lower income bracket while a smaller portion move into the upper tier. At the same time, research from psychologists and economic experts indicates a rising correlation between economic downturns and mental health struggles. Since 2000, diagnoses of anxiety, depression, and other mental health conditions have increased with each major recession, particularly following the 2020 COVID pandemic. These trends highlight the deep financial and psychological impact of economic instability on American households.
By taking proactive steps to prepare for economic downturns and unexpected financial challenges, you won’t just experience greater peace of mind— you can THRIVE— You’ll place yourself in the position to seize opportunities to grow your wealth.
“By failing to prepare, you are preparing to fail.”
~ Benjamin Franklin
“If you don’t own Gold, you know neither history nor economics.”
~ Ray Dalio, Hedge Fund Manager at Bridgewater Associates
The Harvard Gold
Group Difference
Your Trusted Gold IRA Company
Harvard Gold Group (HGG) holds an A+ rating with the BBB and holds 5-star ratings on all major review sites.
HGG is the first gold dealer in America to provide customers the more “expensive" specialty coins at the same low range cost we offer for bullion coins. Don’t pay more for numismatic, semi numismatic, or collector coins.
We do not employ commissioned salespeople or bonused managers— ensuring that your goals, not sales quotas, are always our top priority.
Clients benefit from free consultations, transparent costs, and metals overviews, lifetime account support for you and your heirs— along with a simple, hassle-free buyback program.
Clients also enjoy direct assistance from HGGs co-owners who, since 2010, have helped Americans move over $100 million into tangible gold and silver, whether for secure direct delivery or retirement accounts / Precious Metals IRAs.